Tag: finance

  • **What Do You Mean “Finance”?: The Evidence Behind the Definition**

    **What Do You Mean “Finance”?: The Evidence Behind the Definition**

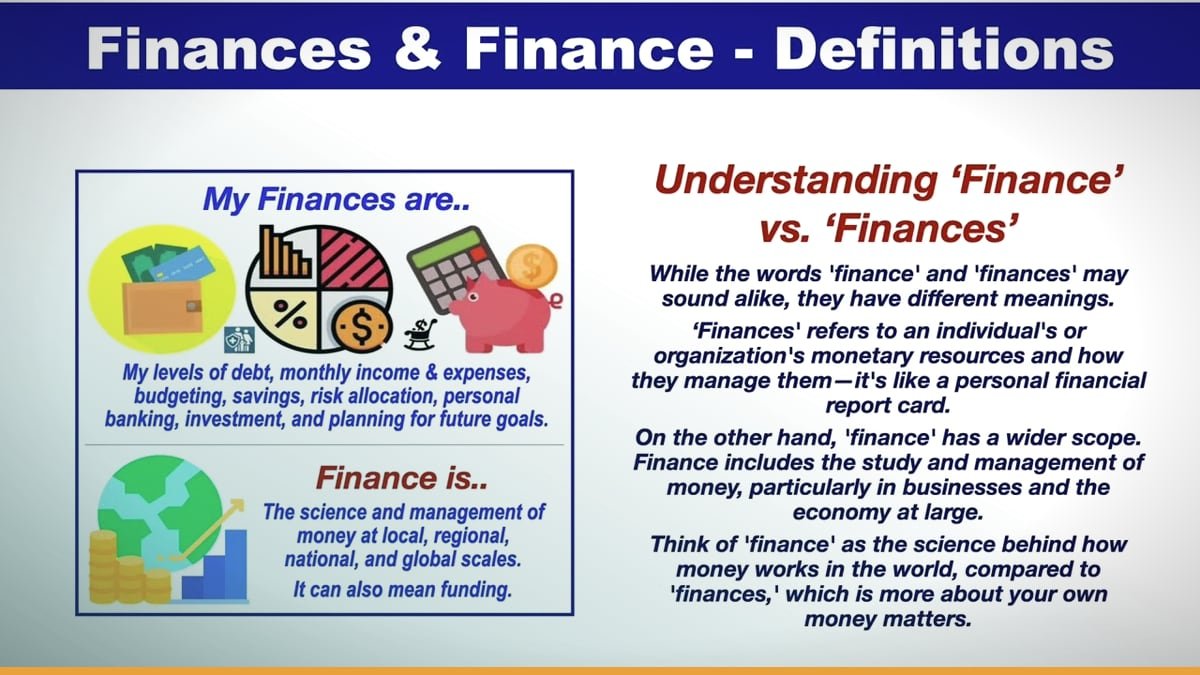
    Header image source: Finances and Finance – definitions and examples via YouTube via Google — cropped to 16:9 and colour-adjusted.

    Key takeaways

    • Finance manages money movement, growth, and allocation at personal, corporate, and government levels
    • It combines practical tools, academic math/statistics, and economic intermediation
    • Distinguishes finance from economics (why markets behave) and accounting (past transactions)

    Finance isn’t just money. It’s the system that decides where money flows, how it grows, and who gets to use it. Forget Wall Street stereotypes—finance is the invisible scaffolding holding up your morning coffee, your mortgage, even your retirement account. It’s the math behind stock prices, the rules behind credit scores, the reason cities build bridges or go bankrupt.

    This isn’t just about dollars and cents. Finance operates on three levels at once: a practical toolkit for managing money, an academic discipline built on math and statistics, and an economic intermediary connecting savers with spenders. Ignore any of these, and you’ve missed the point entirely.


    What "Finance" Actually Means

    Finance is the management of money—specifically, the activities that make money move, multiply, or vanish. Investopedia breaks it down: earning, saving, investing, borrowing, planning. Merriam-Webster keeps it simple: "money or other liquid resources of a government, business, group, or individual. " Corporate Finance Institute (CFI) expands it: "investing, borrowing, lending, budgeting, saving, and forecasting. "

    But here’s the critical distinction: finance isn’t about having money. It’s about the mechanisms that allocate it. That $300,000 bank loan for your house? Finance. The algorithm deciding your creditworthiness? Finance. The statistical model predicting your likelihood of default? Still finance. Even your choice to funnel $200 into a retirement account instead of blowing it on a weekend getaway—that’s finance in action.

    Wikipedia gets it right: finance is both the management of money and the academic discipline studying it. That second part matters. Without the math, the statistics, the analytical tools, finance would be nothing more than educated guesswork.


    The Three Core Functions of Finance

    Finance performs three essential roles. Overlook any of them, and you’ve fundamentally misunderstood the concept.

    1. Finance as a Toolkit

    This is the practical side—the budgeting, saving, investing, borrowing that most people associate with "personal finance" or "corporate finance. " Investopedia and Robinhood both emphasize this angle. Finance is the daily work of managing money.

    You open a high-yield savings account. Finance. You take out a student loan. Finance. You buy Apple stock. Also finance. These aren’t just transactions. They’re deliberate decisions made within a structured system designed to allocate resources efficiently.

    2. Finance as an Academic Discipline

    Here’s where it gets technical. JSU’s Business School curriculum reveals the depth: finance students need "a mixture of math and statistics classes" alongside communication courses. Why? Because finance isn’t just about moving money—it’s about predicting how money will move.

    • Mathematics: Time value of money (a dollar today isn’t worth the same as a dollar tomorrow), compounding, discounting. These principles underpin everything from loan interest calculations to stock valuations.
    • Statistics: Risk assessment (how likely is this borrower to default?), regression analysis (what factors predict stock prices?), probability modeling. Without these tools, finance would be flying blind.
    • Communication: Translating data into actionable strategies. A financial analyst doesn’t just crunch numbers—they explain why those numbers matter to executives, clients, or policymakers.

    Strip away these tools, and finance becomes little more than superstition—guesswork dressed up in spreadsheets.

    3. Finance as an Economic Intermediary

    This is the invisible engine driving economic activity. InternationalStudent.com calls finance "a means by which individuals, companies, and governments facilitate activity and transactions in the marketplace. " In plain terms: finance connects people who have money with people who need it.

    • Banks take deposits from savers and lend them to homebuyers.
    • Stock markets let companies raise capital by selling shares to investors.
    • Governments issue bonds to fund infrastructure, paid back with future tax revenue.

    Without finance, economic activity would collapse. No loans, no investments, no growth. We’d be stuck in a barter economy—trading chickens for grain instead of swiping a credit card for groceries.


    The Activities That Define Finance (And What They Exclude)

    Not everything involving money qualifies as finance. Here’s what is finance:

    1. Investing: Allocating money to generate returns. Stocks, bonds, real estate, venture capital—all firmly within finance’s domain.
    2. Borrowing/Lending: Debt instruments like loans, mortgages, bonds. That car loan you took out? Finance.
    3. Budgeting/Saving: Planning how to spend and preserve money. Your monthly budget? Finance. Your emergency fund? Also finance.
    4. Forecasting: Using data to predict financial outcomes. Cash flow projections, market trend analysis, risk modeling—all finance.

    Here’s what finance isn’t:

    • Economics: Economics studies why markets behave (inflation, unemployment, supply and demand). Finance studies how to navigate them (investing, risk management, valuation).
    • Accounting: Accounting records past transactions (balance sheets, income statements). Finance plans future ones (capital budgeting, mergers, working capital).
    • Informal money handling: Lending $20 to a friend isn’t finance. Lending $20,000 with a legally binding contract is finance.

    Finance as an Academic Discipline: The Technical Backbone

    Finance isn’t about intuition—it’s about precision. JSU’s curriculum offers a glimpse into how deep this goes:

    • Time value of money: A dollar today is worth more than a dollar tomorrow because it can be invested. This principle underpins everything from loan interest calculations to stock valuations.
    • Risk assessment: Finance uses statistical models to quantify uncertainty. Value at Risk (VaR), for example, estimates how much a portfolio could lose in a bad market.
    • Regression analysis: Identifying relationships between variables (e.g..
    • Communication: Translating data into actionable insights. A financial analyst doesn’t just run numbers—they explain why those numbers matter to decision-makers.

    Without these tools, finance would be like navigation without a compass—you might eventually reach your destination, but you’ll waste time, money, and energy getting lost along the way.


    Finance as an Intermediary: The Invisible Engine of the Economy

    Finance doesn’t just manage money—it moves it. InternationalStudent.com describes it as "a means by which individuals, companies, and governments facilitate activity and transactions. " Here’s how that works in practice:

    • Banks: Pool deposits from savers and lend them to borrowers. Without banks, you’d have to find someone with $300,000 who trusts you enough to lend it for 30 years.
    • Stock markets: Let companies raise capital by selling ownership stakes. Without stock markets, startups would be limited to wealthy individuals or banks for funding.
    • Bonds: Let governments and corporations borrow directly from investors. Without bonds, infrastructure projects would be constrained by whatever tax revenue exists in a given year.

    This intermediation is why finance is often called the "plumbing" of the economy—it’s not glamorous, but when it breaks, everything grinds to a halt.


    The Scope of Finance: Who Uses It and Why

    Finance isn’t just for Wall Street traders. It’s everywhere:

    • Individuals: Personal finance—saving for retirement, investing in index funds, managing debt. Robinhood’s definition emphasizes this: "everything that has to do with managing money. "
    • Businesses: Corporate finance—capital budgeting (should we build a new factory?), mergers and acquisitions, working capital management (how do we pay suppliers while waiting for customers to pay us?).
    • Governments: Public finance—taxation, debt issuance, fiscal policy. When a city issues municipal bonds to build a bridge, that’s finance.
    • Global markets: International finance—currency exchange, cross-border investment, sovereign debt. When a U.S. company buys a factory in Germany, finance determines the cost in dollars.

    Rasmussen University sums it up: finance is "a broad term that encompasses the many ways people, businesses, and governments approach managing money. " The methods differ, but the goal remains the same: allocate resources efficiently.


    The Evolution of Finance: From Barter to Algorithms

    Finance didn’t begin with stock markets or credit cards. It started with barter—trading goats for grain. Then came coins, banks, joint-stock companies, derivatives, high-frequency trading.

    Key shifts:

    1. From physical to digital: Money used to be gold or paper. Now it’s mostly 1s and 0s in a database.
    2. From local to global: A bank in New York can lend to a farmer in Kenya. A company in Tokyo can issue bonds denominated in euros.
    3. From human to algorithmic: Trading floors used to be packed with shouting brokers. Now, most trades are executed by algorithms in milliseconds.

    CFI’s inclusion of "forecasting" hints at this evolution. Modern finance isn’t just about moving money—it’s about predicting where money will go next. Machine learning models now forecast stock prices, credit risk, and fraud. Blockchain is redefining how transactions are recorded and verified. Finance is no longer just about money—it’s about information.


    The Limits of the Definition: Where Finance Ends and Other Fields Begin

    Finance doesn’t exist in isolation. It overlaps with other disciplines but remains distinct.

    • Finance vs. Economics: Economics studies why markets behave (e.g.. Finance studies how to navigate them (e.g..
    • Finance vs. Accounting: Accounting records what has happened (e.g. Finance plans what will happen (e.g..
    • Finance vs. Wealth Management: Wealth management is a subset of finance focused on personal investing (e.g..

    Mislabeling these distinctions creates confusion. Calling finance "just money" ignores its strategic, predictive, and intermediary roles. It’s like calling surgery "just cutting"—it misses the skill, planning, and purpose behind the act.


    Why This Definition Matters: The Stakes of Getting It Wrong

    Finance isn’t an abstract concept—it’s the difference between prosperity and ruin.

    • For individuals: Misunderstanding finance leads to poor decisions—taking on too much debt, saving too little, chasing high-risk investments. Robinhood’s definition emphasizes this: finance is "everything that has to do with managing money. " Get it wrong, and you might end up broke.
    • For businesses: Flawed financial models can cause bankruptcies. Enron’s collapse wasn’t just about fraud—it was about bad finance (off-balance-sheet entities, overvalued assets). CFI’s inclusion of "forecasting" is a reminder: finance is about predicting the future, and bad predictions have real consequences.
    • For governments: Poor fiscal management leads to crises. Greece’s debt default in 2012 wasn’t just about spending too much—it was about borrowing in euros while having a weak economy, a classic finance mistake.

    The Big Question: Is Finance Just a Tool, or Is It the System Itself?

    Finance is often described as a "tool"—something we use to achieve other goals (retirement, homeownership, economic growth). But what if finance isn’t just a tool? What if it’s the operating system of the modern economy?

    Consider the evidence:

    • Every economic transaction relies on finance (loans, payments, investments).
    • Every major policy decision involves finance (taxes, spending, debt).
    • Every technological innovation is funded by finance (venture capital, IPOs, corporate R&D).

    You’re missing the bigger picture entirely.

    So here’s the open question: Is finance a means to an end, or is it the end itself? And if it’s the latter, what does that mean for how we regulate it, teach it, and participate in it? The answer shapes everything from personal financial literacy to global economic policy. And right now, we’re not even asking the question.
  • **What Is Finance Cost? The Hidden Engine of Corporate Debt and Performance**

    **What Is Finance Cost? The Hidden Engine of Corporate Debt and Performance**

    Header image: 45th CPTS photos (8046917).jpg) by U.S. Space Force photo by Airman Collin Wesson, Public domain, via Wikimedia Commons — cropped to 16:9 and colour-adjusted.

    Key takeaways

    • Finance cost covers all corporate borrowing expenses, not just interest
    • Dynamic discounting shifts costs to operating activities, distorting cash flow
    • Rising rates and transparency demands will reshape finance cost management

    Finance cost is the total expense a company pays to borrow money. That’s it. Not just interest—though interest is usually the biggest chunk. It’s fees, discounts, prepayment penalties, every charge that appears when you tap a credit line, issue a bond, or factor an invoice. Look at a cash-flow statement under “financing activities,” and that number is the full price of debt. Not a subset. The whole bill.

    Most companies don’t break it down. You won’t find a footnote splitting interest from origination fees from late-payment penalties. That opacity makes finance cost the most underappreciated lever in corporate finance. Miss it, and you misread profitability, cash flow, even solvency.


    The Anatomy of Finance Cost: What’s In There (and What’s Buried)

    Interest gets the headlines. The rest matters just as much.

    • Interest: The biggest line item. A percentage of principal.
    • Fees: Origination fees (1–2% of the loan), commitment fees (charged on undrawn credit lines), late fees. These fees can push the effective cost well above the stated rate.
    • Non-interest charges: Discounts on invoice factoring (1–3% of invoice value), prepayment penalties, admin charges. Cash-flow finance costs often include a charge similar to interest, calculated as a percentage of the loan.
    • Hidden costs: Dynamic Discounting—early-payment incentives for suppliers—doesn’t cut gross finance costs but shifts them into operating activities. This approach can inflate operating cash flow, masking the true cost of debt.

    Example: A $10 million loan at 5% interest with a 2% origination fee. Nominal interest cost: $500,000. Add the $200,000 fee, and the effective finance cost jumps to 7%. Most companies won’t disclose the fee separately. It’s buried in the total.


    How Finance Costs Are Recorded: The Cash Flow Statement Trick

    Finance costs belong in the financing activities section of the cash flow statement. That’s the rule. Rules have exceptions.

    • Standard treatment: Interest paid, loan fees, and other borrowing costs flow through financing activities. This keeps operating cash flow clean, reflecting core business performance.
    • The Dynamic Discounting exception: When companies use this method, a portion of finance costs—specifically, the discounts offered to suppliers—can appear in operating activities instead. This is a growing trend, especially in industries with long payment cycles like manufacturing and retail.

    Why it matters: Misclassification distorts operating cash flow. A company using Dynamic Discounting might show stronger operating cash flow than a peer with identical debt levels, simply because it’s shifting finance costs off the financing line. Not fraud. Accounting. But it complicates comparisons.


    What Drives Finance Costs? The Variables That Shape the Bill

    Finance costs aren’t static. They’re shaped by internal decisions and external conditions.

    • Credit rating: The single biggest driver. A BBB-rated company might pay 3% more than an AAA-rated one for the same loan. Creditworthiness dictates lender terms.
    • Loan type: Secured loans (mortgages, asset-backed lines) cost less than unsecured debt. Collateral reduces risk, which means lower rates.
    • Market conditions: Benchmark rates (LIBOR, SOFR) set the floor. Economic timing matters—companies that locked in low rates before 2022 are paying less than those borrowing today.
    • Security: Unsecured loans come with premiums. A revolving credit facility with no collateral might carry a 2% fee on top of the interest rate.
    • Timing: Credit availability fluctuates. During tight markets, even strong companies see finance costs spike.

    Case study: Two FMCG firms borrow $50 million each. One has an A credit rating and secures the loan with inventory. The other has a BB rating and borrows unsecured. The first pays 4% interest and a 0.5% fee. The second pays 7% interest and a 2% fee. Over five years, the finance cost gap widens to $7.5 million—all else being equal.


    Finance Costs in Action: How Companies Slash (or Struggle With) the Bill

    Q1 2024 was a masterclass in finance cost management. Or failure.

    • The winners:
    • Guinness Nigeria slashed finance costs by 81.42%. This reduction likely resulted from debt repayment and refinancing.
    • BUA Foods cut costs by 72.30%, while Nestlé Nigeria reduced them by 27.88% (N16.92 billion vs. N23.47 billion).
    • Nigerian Breweries trimmed 46.09% (N8.28 billion vs. N15.36 billion).
    • The outlier: Honeywell Flour Mills saw no change, holding steady at N3.90 billion. That’s not a win. It’s stagnation. Likely due to inflexible loan terms or stagnant debt levels.

    How did the winners do it? PunchNG’s reporting points to three levers:

    1. Debt repayment: Paying down high-cost loans directly reduces finance costs.
    2. Refinancing: Swapping expensive debt for cheaper alternatives (e.g., replacing a 10% bond with a 6% loan).
    3. Negotiation: Renegotiating fees or covenants with lenders.

    The losers? Companies with poor credit, rigid loan structures, or no access to cheaper capital. Honeywell Flour Mills’ flat finance cost suggests it’s stuck with the same debt at the same rates. No refinancing. No repayment. No leverage.


    Finance Cost vs. Finance Charge: Why the Distinction Matters

    Finance cost and finance charge sound the same. They’re not.

    • Finance cost: The comprehensive expense of corporate borrowing. Interest, fees, other charges. Recorded in the cash flow statement under financing activities. It encompasses the interest costs and other fees given to debt financers.
    • Finance charge: A subset, mostly used in consumer finance. It represents the total cost of borrowing money, including both the interest rate and any associated administrative fees. It’s what you see on a credit card statement, disclosed as an APR.

    Key difference: Transparency. Consumer finance charges are regulated and disclosed. Corporate finance costs are rarely broken down. A company might report $100 million in finance costs without specifying how much went to interest, fees, or penalties. That lack of detail forces investors to estimate effective borrowing costs, introducing risk into valuations.


    The Investor’s Lens: Why Finance Costs Are a Debt-Management Litmus Test

    Finance costs are a diagnostic tool. High or rising costs signal trouble. Low or falling costs suggest discipline.

    Debt servicing ability is a core concern for investors. A company with finance costs equal to 10% of revenue is less resilient than one at 3%. EBITDA-to-interest coverage ratios are standard, but finance costs (including fees) give a fuller picture.

    • Trend analysis: A rising finance cost trend is a red flag. It might indicate overleveraging, deteriorating creditworthiness, or exposure to variable rates. Falling finance costs suggest debt repayment, refinancing, or improved credit.
    • Benchmarking: Comparing finance costs across peers reveals competitive advantages. A company with lower costs might have stronger credit, better collateral, or more favorable loan terms.

    Example: Two retailers report $1 billion in revenue. Retailer A has $30 million in finance costs. Retailer B has $100 million. All else being equal, Retailer A is better positioned to weather a downturn. The finance cost gap isn’t just a line item. It’s a buffer.


    Innovations in Managing Finance Costs: Dynamic Discounting and Beyond

    Dynamic Discounting is the most talked-about innovation in finance cost management. It’s also the most misunderstood.

    • How it works: Companies offer suppliers early payment in exchange for a discount (e.g., 2% off if paid in 10 days instead of 30). The discount reduces the supplier’s cost of capital, while the buyer improves working capital.
    • The accounting quirk: The discount isn’t recorded as a finance cost. It’s netted against operating cash flow. This approach can inflate operating cash flow, making the company appear more liquid than it is.
    • Adoption trends: Growing in industries with long payment cycles like manufacturing and retail. It’s not a silver bullet—suppliers must participate—but it’s a low-risk way to optimize cash flow.
    • Limitations: It doesn’t reduce gross finance costs. A company still pays the same interest on its debt. It’s just shifting some costs off the balance sheet.

    Beyond Dynamic Discounting, AI-driven cash flow forecasting is emerging as a tool to time debt issuance or refinancing. By predicting cash flow gaps, companies can avoid borrowing at peak rates or tap cheaper capital when it’s available.


    The Future of Finance Costs: What’s Next?

    Three trends will shape finance costs in the coming years.

    1. Rising rates: Central banks aren’t done tightening. Companies with variable-rate debt will see finance costs climb, pressuring margins. The FMCG firms that slashed costs in Q1 2024 may face a reversal if rates stay high.
    2. Transparency demands: Investors are pushing for more granular disclosures. Expect pressure on companies to break down finance costs into interest, fees, and other charges. Regulators might even step in—IFRS or GAAP could mandate more detail.
    3. Tech-driven optimization: AI and machine learning will play a bigger role in managing finance costs. Predictive models could help companies time debt issuance, negotiate better terms, or identify refinancing opportunities before costs spiral.

    The open question: Will accounting standards catch up? Dynamic Discounting’s rise shows how quickly finance cost management is evolving. But the rules haven’t kept pace. If more companies shift finance costs into operating activities, investors could lose visibility into the true cost of debt. That’s a problem for markets. Not just accountants.


  • **What Is the Definition of Finance? A Rigorous Breakdown of Money, Management, and Meaning**

    **What Is the Definition of Finance? A Rigorous Breakdown of Money, Management, and Meaning**

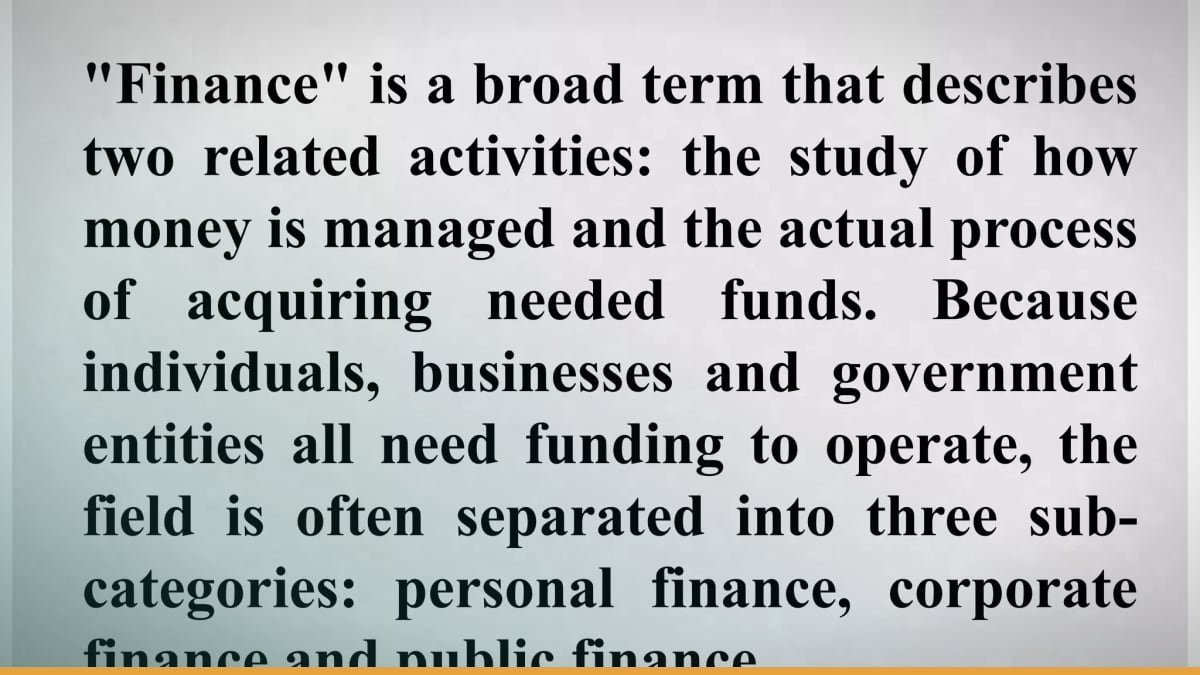
    Header image source: Finance, meaning, concept and types | PPTX via Slideshare via Google — cropped to 16:9 and colour-adjusted.

    Key takeaways

    • Finance is acquiring, allocating, and optimizing resources under risk
    • Applies to personal, corporate, and public contexts
    • Risk, time, and behavior are core dimensions

    One dictionary defines finance as "money or other liquid resources. " Another definition describes finance as "money management including investing, saving, borrowing, and budgeting. " Closer, but still missing the engine. One source includes "investments" as a separate category, which at least hints at growth. One academic source calls finance both an art and a science—finally, someone acknowledges the messiness. One platform defines finance broadly as "everything that has to do with managing money. " Too broad. Another dictionary narrows the definition to debt. That’s not finance. That’s a loan application.

    None of these definitions capture what finance actually does. They describe components but ignore the system. Finance isn’t a static inventory. It’s a dynamic process—acquiring, allocating, optimizing—all under conditions of risk and scarcity, stretched across time. Without risk, finance collapses into accounting. Without time, it’s just arithmetic. And without behavior, it’s a spreadsheet with no humans.


    The Academic Discipline: Where Models Meet Messiness

    One encyclopedia defines finance as "the management, movement, investment, and raising of money. " Process-oriented, but sterile. The "art and science" framing is better—it acknowledges the tension. The science relies on models: CAPM, Black-Scholes, stochastic calculus. The art fills the gaps where models fail—judging management quality in private equity, timing exits, deciding whether to pursue an acquisition.

    This duality explains the field’s persistent debates. Is finance predictive or narrative-driven? Active vs. passive investing hinges on this. The efficient market hypothesis assumes prices reflect all information, but behavioral finance shows humans aren’t rational. Tools like NPV and WACC are rigorous, but their application requires judgment. A CFO’s discount rate isn’t just math—it’s a statement about risk tolerance.


    The Three Branches: Same Principles, Different Stakes

    One source splits finance into personal, corporate, and public. Same core principles—acquisition, allocation, optimization—but wildly different scales and objectives.

    Personal finance is where most people first encounter it. Some sources focus on "budgeting, saving, borrowing"—mortgages, retirement, emergency funds. The question: How do individuals optimize limited resources over time? Various frameworks and rules—these are tools to answer it. The stakes are existential: poor decisions lead to bankruptcy; good ones build generational wealth.

    Corporate finance shifts to firms. Some sources describe corporate finance as "raising, spending, and investing money" to maximize shareholder value. This means capital budgeting (NPV, IRR), capital structure (debt vs. equity), dividend policy. The question: How do firms deploy resources to generate returns? Startups raise capital to scale; mature companies issue bonds for various purposes. Metrics differ—ROIC, WACC—but the goal is the same: growth under constraints.

    Public finance deals with governments. One source frames public finance as "management of government revenues and expenditures"—taxation, sovereign debt, fiscal policy. The question: How do governments stabilize economies while funding public goods? Keynesian economics vs. austerity. Tools like fiscal multipliers and credit ratings balance equity and stability. The objective isn’t profit—it’s societal welfare.

    The unifying thread is allocation under scarcity. The divergence is just as important. What’s optimal for a corporation—leveraging debt to boost ROIC—can be catastrophic for an individual. The definition of finance must be context-aware.


    The Core Functions: More Than Just Moving Money

    One definition that includes "management, movement, investment, and raising of money" hints at finance’s functions but lacks precision. Let’s break it down:

    Acquiring funds isn’t just borrowing. It’s equity (IPOs, venture capital), grants, crowdfunding, taxation. Startups raise capital; governments issue bonds. The common thread: securing liquid resources to meet obligations or pursue opportunities.

    Allocating funds is where finance becomes strategic. Some definitions mention "budgeting" and "spending," but the tools are more nuanced. Capital budgeting (NPV, IRR) helps firms prioritize projects. Portfolio theory (Markowitz) guides asset allocation. The challenge is prioritization—R&D vs. dividends, college vs. vacation.

    Optimizing funds is the dynamic layer. Some definitions mention "investments" and "managing money," but the mechanisms are diverse. Optimization is about adjusting over time—rebalancing portfolios, refinancing debt, exploiting arbitrage.

    Most definitions omit risk transfer—insurance, CDS, securitization. Without it, finance would be zero-sum. Risk transfer allows specialization: banks take credit risk, insurers take longevity risk, investors take market risk. It’s the invisible glue holding the system together.


    Risk: The Silent Fourth Function

    No definition in the brief names risk, yet it underpins every financial decision. Borrowing is risk transfer. Investing is risk-adjusted returns. Budgeting is risk mitigation. Even saving for retirement involves longevity risk.

    Risk manifests in three dimensions:

    1. Market risk: Asset price volatility—stock crashes, interest rate changes.
    2. Credit risk: Default probability—bond defaults, loan delinquencies.
    3. Operational risk: Fraud, system failures—rogue traders, cyberattacks.

    Key frameworks formalize risk management:

    • Modern Portfolio Theory (MPT): Diversification reduces unsystematic risk.
    • CAPM: Beta measures systematic risk.
    • Black-Scholes: Volatility as a pricing input.

    Context shapes risk. Personal finance deals with longevity risk (annuities) and health expenses. Corporate finance focuses on bankruptcy risk (Altman Z-score) and liquidity risk (working capital). Public finance grapples with sovereign default risk (credit ratings) and fiscal sustainability. The tools differ, but the principle is the same: finance exists because the future is uncertain.


    Time: The Invisible Dimension

    No definition mentions time, yet finance is inherently forward-looking. Investing sacrifices present consumption for future returns. Borrowing brings future income to the present. Saving defers consumption. The time value of money formalizes this: $1 today isn’t $1 tomorrow. Discount rates quantify the tradeoff—higher rates reflect greater impatience or risk.

    Key concepts illustrate finance’s intertemporal nature:

    • DCF: Values future cash flows in today’s dollars.
    • Duration: Measures a bond’s sensitivity to interest rate changes.
    • Life-cycle hypothesis: Individuals smooth consumption over their lifespan.

    Tools for intertemporal optimization:

    • Yield curves: Reflect expectations of future interest rates.
    • Pension fund liabilities: Match assets to long-term obligations.
    • Dynamic programming: Optimizes decisions over time (retirement planning).

    Finance isn’t about historical data—it’s about predicting and shaping future outcomes. Historical returns inform models, but the goal is to allocate resources today to maximize tomorrow’s value.


    Institutions: The Backbone of the System

    One definition’s mention of "movement of money" hints at finance’s systemic nature. It relies on institutions—banks, capital markets, regulators—to facilitate transactions, manage risk, and aggregate information.

    Key players:

    • Banks: Deposits, loans, fractional reserve system.
    • Capital markets: NYSE, Nasdaq, bond markets.
    • Non-bank intermediaries: Private equity, hedge funds, insurers, fintech.
    • Regulators: SEC, Federal Reserve, Basel Committee.

    Institutions serve critical functions:

    1. Liquidity provision: Market makers ensure assets can be bought and sold.
    2. Information aggregation: Price discovery reflects collective knowledge.
    3. Risk pooling: Insurance and securitization spread risk.

    Financial crises reveal the system’s fragility. Institutions optimized for efficiency (HFT) but ignored systemic risk (mortgage-backed securities). Finance is a network—individual decisions aggregate into market-wide outcomes. A mortgage borrower’s default can trigger systemic risks.


    Behavior: Where Psychology Breaks the Models

    No definition accounts for behavior, yet humans aren’t rational. Prospect Theory shows people overweight losses relative to gains—explaining panic selling and insurance over-purchasing. Other anomalies:

    • Herding: Investors follow the crowd (meme stocks).
    • Overconfidence: Traders think they can beat the market (they can’t).
    • Disposition effect: Selling winners too early, holding losers too long.

    Behavioral biases distort markets:

    • Momentum effect: Assets that perform well continue to do so.
    • Hyperbolic discounting: Preferring smaller, immediate rewards over larger, delayed ones.
    • Anchoring: Relying too heavily on the first piece of information (IPO price).

    Tools to account for behavior:

    • Nudges: Auto-enrollment in 401(k)s.
    • Robo-advisors: Algorithmic rebalancing to counteract emotions.
    • Regulatory safeguards: Circuit breakers, short-selling restrictions.

    Finance isn’t physics. Models assume rationality, but humans are emotional, biased, and error-prone. The definition must include behavior as a first-order variable.


    The Future: AI, Crypto, and the Redefinition of Finance

    Traditional definitions predate DeFi, AI-driven finance, and CBDCs. These innovations redefine core functions:

    Acquisition:

    • DeFi: ICOs, yield farming (vs. IPOs, bank loans).
    • CBDCs: Digital dollars, euros, yuan (vs. physical cash).

    Allocation:

    • AI: Portfolio optimization (vs. human managers).
    • Smart contracts: Self-executing agreements (vs. legal contracts).

    Optimization:

    • HFT: Millisecond arbitrage (vs. buy-and-hold).
    • On-chain credit scoring: Decentralized risk assessment (vs. FICO).

    Key questions:

    • Is DeFi finance if it removes intermediaries? Yes—it still allocates capital under risk.
    • Is AI finance if it automates decisions? Yes—it still manages money, but with machine learning.

    The definition must adapt. Code (smart contracts) and data (alternative credit scoring) are becoming as important as stocks and bonds. The future is decentralized, automated, and algorithmic—but the core principles remain: acquiring, allocating, optimizing resources under risk.


    The Unified Definition

    Finance is the discipline and practice of acquiring, allocating, and optimizing liquid resources under conditions of risk and scarcity across time and contexts—personal, corporate, and public—to achieve economic objectives.

    Why this works:

    1. Comprehensive: Captures all core functions and dimensions—risk, time, behavior, institutions.
    2. Context-aware: Applies to individuals, firms, governments.
    3. Dynamic: Accommodates traditional finance and emerging tools (DeFi, AI).
    4. Operational: Distinguishes finance from economics (aggregates) and accounting (historical records).

    Finance isn’t just about money—it’s about making money work. The definitions in the brief converge on this, but the full picture emerges only when we layer in risk, time, behavior, and institutions. The next frontier? How finance evolves as technology redefines liquidity, intermediation, and trust. Will the future be decentralized, automated, algorithmic? The answer depends on whether we adapt the definition without losing sight of its purpose.